Blog

  • A third aircraft carrier for India: Budget versus necessity

    A third aircraft carrier for India: Budget versus necessity

    Category: Defence Policy, Military Power & Modernisation

    Title: A Third Aircraft Carrier for India: Budget vs necessity

    Author: M Matheswaran  02.06.2020

    The Indian military is undergoing what may be its most significant reorganisation since India’s independence, with considerable implications for its future strategic posture. One important issue that has been brought to the fore is the role of the Indian Navy as a regional power projection force built around three aircraft carriers. The government’s decision on this issue will have significant implications for the region.


    Read More

  • Vietnam: Economic Prospects in Post Second Wave Covid-19

    Vietnam: Economic Prospects in Post Second Wave Covid-19

    The global community is into the ninth month of the COVID-19 pandemic and international efforts to develop a vaccine are at advanced stages.  Meanwhile in Russia over 250 Moscow residents received a dose of Sputnik V[i] and the Chinese Center for Disease Control and Prevention (CDC) has announced that the vaccine will be ready by November this year.[ii]Similarly, many American, British, European, and Indian companies are developing the vaccine which is at different levels of trials.  While the above progress is very encouraging, the global COVID-19 infections continue to rise and as on 13 October, according to the World Health Organisation (WHO), the total confirmed cases of COVID-19 were 37,601,848 people including 1,077,799 deaths.[iii] The top four countries with the highest infections were the US, India, Brazil and Russia.

    Vietnam’s COVID response since 23 January 2020, when the first case was detected, has been noteworthy. It successfully contained the spread of the virus by instituting local quarantine measures in early stages, declaring a state of emergency in February, and banning flights to and from China. For the next two months, Vietnam maintained strict COVID related measures including national lockdown and it was only in late April that some restrictions were removed in localities if they had contained the virus; but non-essential public services remained suspended. The opening up continued slowly with the resumption of flights to select destinations and cross-border travel restrictions were lifted. Meanwhile, Vietnam registered to buy a Russian Covid-19 vaccine as also developing vaccine on its own.

    In August, the second largest COVID-19 outbreak (after Danang) was reported in Quang Nam Province. The ‘second wave’ has now been successfully controlled.

    However, in July, Danang, a tourist hotspot, reported several new cases and a massive evacuation of nearly 80,000 tourists was undertaken. In August, the second largest COVID-19 outbreak (after Danang) was reported in Quang Nam Province. The ‘second wave’ has now been successfully controlled. As of 15 September, in Vietnam (total population 95,540,000) there were 1063 cases; 35 deaths; 261,004 tests had been conducted, and 11cases per million was recorded.[iv]

    Vietnam’s economic outlook in the ‘post-COVID Second Wave’ is a mixed bag of opportunities and challenges. There are at least four issues which merit attention. First, the Vietnamese economy, like any other global economies, suffered due to the pandemic. The 2020 first-half growth was about 1.8% compared with 7% in 2019 (year-on-year), but the Vietnamese economy has shown enormous resilience when compared with major global economies who have recorded negative growth. This is due to the proficient handling of the pandemic and the country is now on a quick and steady recovery path. The HSBC has revised Vietnam’s 2020 growth forecast from 1.6% to 3.0%.[v]

    It is also important to mention that the Vietnamese government has offered attractive incentives to multinational investors to help them “move up the value chain” and build supply chains in the country.

    Second, there are clear signs that Vietnam continues to be an attractive destination for foreign investments. This trend is not only due to global conglomerates moving out of China and seeking new destinations with attractive options for setting up of their businesses, but Vietnamese handing of the pandemic has provided them enormous business confidence in the country. According to the Ministry of Planning and Investment, total foreign investment in the first half was worth US$18.47 billion.[vi] Japanese (Panasonic), South Korean (LG Electronics), US (Foxconn; Apple) and the European (Heineken) companies moved to Vietnam. It is also important to mention that the Vietnamese government has offered attractive incentives to multinational investors to help them “move up the value chain” and build supply chains in the country.

    Third, is about renewable energy. Vietnam’s current energy generation mix is skewed towards coal (18,516 MW) and hydrocarbons (8,978 MW). Notwithstanding the COVID-19, the country’s average electricity consumption per day during the first few months of 2020 was 615 million KWh, an increase of 7.5 per cent compared with 2019.[vii] It is estimated that “Vietnam’s energy demand will increase by over 10 per cent by the end of 2020, followed by an eight per cent growth per year in 2021 to 2030.” The “government wants to reduce its greenhouse gas emissions by eight per cent by 2030” for which investments in renewable sources of energy such as solar and wind would have to be made,

    Fourth, is about immersion in Industry 4.0 technologies. There are now clear trends of widespread digital transformation across the globe and is impacting every aspect of the industry from commercial operations, technology management, use in fintech to support banking and financial services, new business models through analytics, and human resource management.  These technologies can potentially boost productivity and improve Vietnam’s GDP. For that innovative national policies for growth are needed. Also, the human resource would require ‘up-skilling, reskilling and retooling’ to embrace these technologies.  The industry leaders too have to recognize the importance of educating themselves and using new technologies as also adopting innovative models for their operations.

    Vietnam should build upon its successes of handling the COVID-19 pandemic and ‘build back better’ by offering long-term stimulus for investments and accord high priority to zero-carbon technologies to spur inclusive and resilient growth.

    Finally, Vietnam should build upon its successes of handling the COVID-19 pandemic and ‘build back better’ by offering long-term stimulus for investments and accord high priority to zero-carbon technologies to spur inclusive and resilient growth. It must adopt strategies for investments in technologies, products and services as also create new jobs tailored for Industry 4.0.


    Notes

    [i] “Russia Covid-19 vaccine: Over 250 people in Moscow get inoculated, says report”, https://www.livemint.com/news/world/russia-covid-19-vaccine-over-250-people-in-moscow-get-inoculated-says-report-11600085464168.html  (accessed 16 September 2020).
    [ii] “China coronavirus vaccine may be ready for public in November: Official”, https://www.hindustantimes.com/world-news/china-coronavirus-vaccine-may-be-ready-for-public-in-november-official/story-1DzVCBrdOwleJXxuw0wvyI.html  (accessed 16 September 2020).
    [iii] “WHO Coronavirus Disease (COVID-19) Dashboard”, https://covid19.who.int/?gclid=CjwKCAjwzIH7BRAbEiwAoDxxTlG5T6XZYiHVHBesW5cmAa9DKUytaVgH01haDH10TpmFA3OP-2s_phoCk9sQAvD_BwE  (accessed 16 September 2020).
    [iv] “Southeast Asia Covid-19 Tracker”, https://www.csis.org/programs/southeast-asia-program/southeast-asia-covid-19-tracker-0#National%20Responses  (accessed 16 September 2020).
    [v] “Vietnam’s positive growth in Q2 defies market expectations: HSBC”, http://hanoitimes.vn/vietnam-positive-growth-in-q2-defies-market-expectations-hsbc-313035.html  (accessed 16 September 2020).
    [vi] “Vietnam expects imminent new wave of foreign investment”, https://www.nationthailand.com/news/30392781?utm_source=homepage&utm_medium=internal_referral  (accessed 15 September 2020).
    [vii] “Assessing Vietnam’s Economic Prospects for Foreign Investors After COVID-19”, https://www.vietnam-briefing.com/news/assessing-vietnams-economic-prospects-foreign-investors-after-covid-19.html/  (accessed 15 September 2020).

    Image: Ho chi-min City

  • InsurTech In India

    InsurTech In India

    It is not an unknown to anyone that the third, or Digital, Revolution, and the Fourth- The Technological Revolution has transformed the world order and the way daily activities are conducted. From a linear to an exponential growth rate of the revolutions, all the sectors- minor and major have seen unprecedented changes. The financial sector, though slow and cautious, is not an exception to these transformations.

    FinTech, or Financial Technology is the integration of technology into the offering of financial service to improve and automate their delivery and usage. Regular activities like online transfer of money to purchase of equity through an online platform come under the umbrella of Fintech. The Global Fintech Market has been valued at $127.66 bn by 2018 and was estimated (before COVID) to grow at 24.7% per annum. India is the 3rd largest fintech centre with FinTech investments of nearly $3.7 bn.

    Financial systems globally have incorporated certain level of digitalization and have experienced growth. One of the major markets that were perceived to have huge potential for Fintech investments is Insurance. Reducing vulnerability to financial loss, mobilization of funds and capital formation, and funding of infrastructural (or long term) projects had made the Insurance sector attractive for both demand-side and supply side parties for centuries, essentially making it a necessary financial instrument. Given this, the insurance penetration in the world is still quite low, and this industry is perceived as ripe for disruption and innovation by the FinTech Start-Ups.

    Insurtech, coined in 2010, is a combination of insurance and Fintech i.e. exploiting the wave of the digital revolution to improve insurance provision, innovation, and cost reduction. Insurtech employs artificial intelligence for customization of insurance products, simplification of pricing and underwriting for the products, cost reduction through disintermediation and automation, easy and quick settlement of claims and provide a platform for innovation. For example, claim settlement in motor insurance could be automized and made digital intensive, by uploading photographs of the accident and relevant documents to verify the claim, and online processing and approval of the claim. Blockchain technology would be of critical here for collaboration and common sharing of data and transactions with other insurance players, to avoid fraud by customer( for example, repetitive claims). Use of technology would also enable extending of services to those previously left out of the system.

    Why InsurTech?

    Say for example, in health insurance, an insurer would obtain only point-in-time data (through medical tests) about the policyholder which is not completely sufficient to make accurate risk assessment and underwriting. Once the customer is on-boarded, there is no effective way an insurer could know or keep track of the risk entailed in activities of the agent. That is the problem of moral hazard[1] which is a most relevant in case of motor insurance (at the individual level) or marine insurance (at the institutional level). InsurTech extract information from repositories like Big Data, BlockChain[2][3] or information records of Technology-driven devices (IoT devices like wearables and trackers) to maintain a regular stream of data that enables them to price the risk better and provide appropriate incentives to customers’ to reduce their risk exposure.

    For example, Pedometers to count steps walked in a day, fitness devices that capture heartbeat, oxygen intake, blood pressure etc, or even information recorded by smartphones (sometimes linked to the wearables) is used as input data that helps insurers to gain better insights(to a limited extent)  into the behavioural pattern of the policyholder. This is additional information available to the tech-driven InsurTechs that gives them an edge over the conventional insurance companies in assessing the risk more accurately. The analysis could be utilized to motivate customers to maintain good health by providing incentives like health-score based reduction in premium or other tangible benefits like discounts on health products, free subscriptions etc.

    There are several types of innovations[4] that fall within the scope of InsurTech—Digital platforms, Internet of Things (IoT), Big Data Comparators, Robo Adviser, Machine Learning, Artificial Intelligence, Blockchain, P2P (peer to peer), Usage-based and so on. India, being one of the largest smartphone users could take advantage of the Existing mobile and digital penetration to extend the outreach of insurance products (life, health, pension schemes) into untapped segments in the country- like youth and low-income customers.

    Risk assessment, underwriting and Fraud detection is done by the analysis of the accumulated data using Artificial intelligence and Machine Learning techniques. Artificial intelligence (AI) refers to the simulation of human intelligence in machines that are programmed to think like humans and mimic their actions. Machine Learning (ML), [5]a subset of Artificial Intelligence, is the science and engineering of making machines ‘learn’ by finding patterns in data in an automated manner, using sophisticated methods and algorithms.

    So how does Insurtech aspire to be the face of the insurance market?

    With the digital revolution and rapid increase in the use of mobile phones, insurtech sees an opportunity to reach out to its customers in a fast and convenient way. Data resources like Big data and SaaS, about the customers collected from multiple sources could be employed to draw better inference from raw data and target the pool of potential customers. Unlike traditional insurance, Artificial Intelligence (AI) and Machine Learning(ML) could be used to develop chat bots and multiply interaction between agent and customer for assessing and customize the products in line with their needs. New Technologies (like Robotic process automation) could be used to reduce human intervention and automate the mundane activities like underwriting the contracts, claim settlement and also reducing operational costs. Moreover, AI and ML enable fraud detection from the pattern of activities of the customer. Unlike established insurers, insurtech have the flexibility to steer clear of legacy products and provide tailor-made products for the customers according to their needs and demand.

    Incumbents, or the established insurers, are viewing this as an opportunity and catalyst of innovation rather than a threat to their market penetration and customer acquisition. Collaboration of incumbents with the nascent start ups is a win-win situation, with the integration of best of both the worlds- the established infrastructure and market share of incumbents and innovative products, niche targeting and better pricing by employing AI and ML algorithms of the Insurtech.

    Insurtech in the World

                US homes nearly half of the InsurTech start-ups, followed by UK and India, and is an avenue for 63% of the insurtech investments.


    Source: InsurTech 2020 , Research Insights by Imaginea


                Some of the innovative on-demand insurance products launched by Insurtech around the world include-

    • MANGO: a Mexican- retirement and life insurance intermediary, for obtaining life insurance in minutes without excessive paperwork and confusing coverages.
    • Go Girl: women-only drivers insurance. It involves lower premiums for good drivers, free courtesy car repairs and an inbuilt accident and theft insurance. Complete transaction is conducted online.
    • VisitorCoverage: a travel medical insurance for only non-US citizens. It also provides insurance for public emergency health screening including Covid-19 and other tests.
    • Fizzy: an mobile insurance for delays in flights for 2hours or more
    • Dapp: Etherisc, a Munich Based insurance platform , offers a crop insurance, providing an instant payout of insurance in case of flood or drought.
    • AgUnity and Etherisc, a austalian start up to provide insurance covers directly to farmers to reduce the last mile challenges in providing insurance to customers who need it.

    InsurTech in India

    Currently, there are 24 life insurance and 39 non- life insurance companies in India (incumbents). In spite of that, India with a population of 121 billion has less that 4% (3.7% to GDP) of insurance penetration and a lapsation rate (unpaid premium for >6 months) as high as 20% compared to 15-20% in other Asian countries. As of 2017, at least 75% or 988 million Indians do not have life cover and 56% of population do not have any significant health coverage (out of 44%, 26% are covered by Rashtriya Swasthya Bima Yojana and only 8% by insurers).

    Incidentally, Indian insurance industry for a long time has relied on one-size-fits-all insurance products in the market, but now the dynamics of the insurance market are changing. Innovative products like usage-based insurance, micro insurance and on-demand insurance are flooding the Indian market. The large section of uninsured population is a candy store of opportunities for competent start ups that are in search of potential markets.

    • Usage based insurance: insurance products with low premium, paid periodically based on usage like pay-per-mile auto insurance; individual habits-based life insurance.
    • Need – based insurance: based on specific needs of the customer like theft insurance when away from home, theft insurance for valuables in the rented house. IRCTC travel insurance – in collaboration with ICICI Lombard, Royal Sundaram and Shriram general. Paytm launches a e-wallet insurance, refunding money stolen or accessed unauthorized.
    • Sachet-size insurance: provision of products like insurance against dengue (dengue insurance) to accident and life insurance, at a low premium rates is the agenda of this insurance.  Toffee Insurance – gurgoan based insurance start up, offers insurance against cycle theft and mosquito related diseases for a premium starting from Rs 20.

    [innovative ideas like Tinder-Date-Gone-Bad insurance to cover for restaurant bills and gift expenses are all our millennials and Gen X need to mobilize some cash for insurance].

    These are the some of the innovative products tailor-made for its customers according to their needs and economy. The primary incentive behind these innovations is to create an environment where customers are introduced to the benefits of insurance, who would ultimately vouch for the long-term insurances.

    Paytm which has users mostly in Tier II and Tier III cities has partnered with insurers to provide insurance services like premium payment and policy renewal and has  launched PayTm Insurance in early 2020, tying up with leading insurance firms in india. Amazon and Flipkart have collaborated with ACKO and AEGON LIFE respectively to provide Point-of-Sale insurance(for example, insurance on electronics). Ola provides commutation insurance for the rides at Rs 1. IRDA and the incumbents have viewed this disruption as an opportunity to improve penetration and provision of service. Collaboration with incumbents would also reduce barriers to trade for the emerging start ups and would provide financial support for more innovations. IRDA granted licenses to AKCO, DIGIT INSURANCE, COCO by DHFL and reliance health insurance to work as “neo-insurers”; a sandbox was established for the initial testing of new innovations before launching them into the market; guidelines and regulations were laid down for the functioning of insurtech, under the supervision of IRDA.

    Though at nascent stage, Insurtech has already attracted $3 billion investments worldwide. India has attracted nearly $183 million investments, as of 2019.


    Source: Predictions, BusinessToday.in 


    Source: Predictions

    IRDAI on Insurtech

                IRDA is the Insurance Regulatory and Development Authority of India. The demand for linking wearables to product designing by the insurers prompted the setting up of a working group to look into the new innovations and wearables. The main purpose/aim of working committee was to make recommendations for supervisory and regulatory frameworks for InsurTech.

    “What should be the Regulator’s role in encouraging innovation”[6]       

    IRDA working committee has recognized that customers’ needs have evolved over time which cannot be fulfilled by traditional insurance alone. IRDA subsequently acknowledged that use of technology will, not only aid in new innovations and better service provision, but also helps insurers assess risk better, develop new business models, processes and products, through the use of data collected through various devices (for example: IoT[7] devices in the automobile to assess policyholders’ driving behaviour, which are recorded as data points). Insurers are embracing innovations with focus on data analytics, and sophisticated data models that help the identify, understand and quantify risk.
    Nevertheless, IRDA also acknowledged that this data capture poses several threats and challenges to the insurer and the customer. IRDA recognized the need for a regulator to understand the fast moving innovations in the sector, and develop proper knowledge and skills that foster Insurtech, simultaneously protecting the customers’ interests. In its report, it has made some recommendations regarding supervisory and regulatory framework with respect to InsurTech – Risk assessment, risk Improvement, product design and product pricing.

    For a better insight into the status quo of InsurTech worldwide, IRDA working committee looked into the variety of measures insurance regulatory bodies in other countries have observed.

    • Financial Conduct Authority (UK): FCA has taken initiative to look out for upcoming start ups and understand their potential problems, alongside with providing direct support (advisory support and clearing regulatory ambiguities); it has established a sandbox for pilot testing of new products on live customers on a small scale.
    • BaFin, Germany: it has adopted a technologically neutral position, i.e no special treatment is accorded to InsurTech owing to their innovative nature. Regulations to the insurers are strictly based on the functions performed by them.
    • Mexico: Regulators felt it is too early for developing separate regulations for Insurtech and they would be supervised under the existing regulations.

    Notable observations

    “From purchasing a policy to raising a claim, the process is time consuming, resource driven, and paper intensive. Technology can address these concerns and make the customer experience very smooth and hassle free.”

    “Digital technology could extend the reach coverage into largely untapped areas such as lower income segments, by reducing costs and allowing businesses to engage with customers in more compelling and relevant ways”

    “The use of technology has an impact on product design and the efficiency of inclusive insurance delivery.”

    “The consent of the customer to share data is a must for participation in such products.”

    “Insurers may be allowed to capture data as per their product requirements, but within the scope of insurance and underwriting need.”

    “The provider shall capture and give the insurance companies only the specified information, and the privacy of data arrangement will be directly between the insured and the provider.”

    “Insurers shall develop robust internal monitoring mechanisms to ensure that data leakages do not take place as this data could be misused for monetary benefits (e.g., sending promotional offers to customer based on his location etc.).”

    “The products can evolve and be tested in a sandbox environment before fully going live and a transition strategy should be proposed for when the proposed product exits the sandbox environment.”

                 Working Committee insisted on maintaining transparency and follow protocol for data collection, data usage and data sharing with third parties. It suggested that there is a need for portability/ sharing of data between the insurers. They could employ block chain technology unto this purpose.

    IRDA permits the insurers to offer discounts or offers to the customer based on the data collected. Premium and other benefits like discounts or subsidized or free health services  could be determined by the performance, progress, and consistency in individual’s (say health) score arrived at by analysing data obtained from single or multiple sources.

    Data Mining and Security

    Data collection could be done through proprietary or third party services. However,

    • Consent and customer access: The insurer should provide the details of the data collected to the customer and he should have access to this data (on a portal etc). There should be complete transparency about the data collected (should be as per/after his consent) and the benefits bestowed.
    • Usage: The usage of data should be as per the notice given to the customers. Regulations have to provide appropriate safeguards against data misuse
    • Disclosure: Insurer should not share the data with any third party, except for analytical services, provided they(analytical firms) satisfy the framework laid down.
    • BlockChain: BlockChain is an effective way to ensure transparency and security (encrypted records-blocks which are resistant to modification of data) which makes them ideal for recording of events and transactions. This is an ideal platform to ensure security and sharing to data among insurers.

    Concerns

    • It is important to maintain a right balance between protection of policyholders’ interest and promoting innovation.
    • There is a chance that some segment of populated may be rendered commercially uninsurable. Risk granulation might worsen the affordability and exclusion of certain sections in the society.
    • Innovations might disrupt the traditional risk pooling mechanism of the incumbents
    • Technology might disrupt the conventional business models of the insurers. There is a possibility of minimized engagement (integration) between insurers and customers.
    • Data insecurity is a prominent challenge.
    • Overreliance on technology could be a threat.
    • Supervisors ought to develop adequate technical resources, knowledge and skills to make sure there are no lapses.

    Recommendations

    • Insurers should perform a cost-benefit analysis, because the cost is ultimately borne by policyholders
    • (As mentioned) Product pricing and premium reviews, incentives to customers can be based on data collected through devices.
    • Such products must be tested in the sandbox before launch in the market.
    • Provision for adding wearbles data pricing for existing products. Details of usage of wearble devices should be a part of product filing.

    Interview

                InsurTech is still newbie. I found it more appropriate to  interview  few analysts who have hands on experience in the insurance market and have worked, supervised or studied about InsurTech and InsurTech start ups.

    I have interviewed 4 analysts

    Dr Sahil: A medical graduate(Cancer Biology) who ventured into Insurance sector. He is a experienced professional with an in-depth knowledge of healthcare and Insurance industry. Had the opportunity to be a part of 4 startups Currently working as a Director in a new and upcoming zen space of Insurtech- Meta InsurTech.

    Aparajit Bhattacharya: Senior-level Insurance professional experienced as Business Head of public and private companies. He is also a seasoned executive with an in-depth understanding of emerging technologies and their commercial applications, also having international business expertise, having conducted business in South Asia, Nigeria. Motivated self-starter who earned multiple sales achievement awards during the early career, as well as sustained recognition for Co-Founded Start-Up- Insure First.

    Rahul Mathur: He has completed his Master’s degree from the University of Warwick. He worked as a  Insurance Product Manager at Laka Insurance focused on product development, strategy and research. Presently, he is based in London working as a consulting analyst for a Start-up lead at the London chapter of Accenture’s FinTech Innovation Lab. He is also an Ambassador for Asia Insurtech Podcast, Asia’s first podcast dedicated to InsurTech and innovation in insurance featuring entrepreneurs, thought leaders and investors.

    Neerav:  Senior-level insurance professional.

    1. Where does insurTech stand today in India?

    Dr.Sahil:  InsurTech is basically employing AI and ML methods, and other technological tools, that reduce human intervention and processing time and increases efficiency in the insurance sector processes. InsurTech can help in early and easy, simplified purchase, processing and settlement of claims. According to me, we haven’t really reached that stage yet. Currently, we are in a behavioural changing phase, through digitalization of insurance Claims processing is still paper intensive (physical documents). The farthest we have gone so far is the approval of sandbox for testing products. But we are still behind in R&D and new products are yet to come out.

    Aparajit: InsurTech is a mix of insurance and technology. Though AI seems like a catchy concept, it hasn’t entered insurance globally. Presently, InsurTech is majorly dominated by Cloud-Based API. In the coming decade, more insurtech start ups and intermediaries will subscribe to using blockchain to automate activities more than AI.

    Neerav: InsuTech is mainly AI driven ecosystem that aids in reducing human intervention, cost and time, and improves accuracy. It cannot be regarded as a separate field. It has touched all areas in insurance so far, from risk analysis to price determination. But we are certainly slower than some countries like Singapore which have been using more advanced technologies.

    Rahul: More incumbents are willing to engage with Start ups to do business for example- partnerships with Riskcovry for distribution via APIs. Situations have changed for the insurance industry. Digit has scaled to $313M GWP for FY20 via commercial lines business. Private players are laying an active role in insurance. InsurTech has penetrated almost all areas in insurance including risk analysis, and price determination.

    1. What has been the Biggest success of InsurTech so far? What more could be done?


    Dr.Sahil: Sandbox is a appaudable success. New products are entering markets right now. But country needs to be more adaptable. As a premium- driven economy, we are attracted to cheaper premium products, which defeats the purpose of insurance. Awareness is still a big challenges in India.

    Aparajit:  One of the major successes is digital customer onboarding ( and acquisition) . Social media and search engines are creating awareness. Specially after covid, awareness about insurance (mostly health) has increased. InsurTech also created a excellent API culture for customer acquisition.

    Secondly, Sandbox is a commendable breakthrough, indicating that regulator is working on creating a conducive environment for growth of insurtechs. IRDA is also promoting e-commerce sales in Insurance. In Additional, various business-to-business start ups that work on administration, customer onboarding have also developed. These are some appreciable successes so far.

    Neerav: Insurers in India have become more adaptive to change and are more open to suggestions, new technologies and actively building internal infrastructure. They are looking for ultimate outcome.

    Rahul: Biggest success of InsurTech so far is lowering operational cost resulting in lower premiums (e.g.how). Secondly, B2B2C (business to business to customer) distribution via new affinity channels like e-commerce and payments apps entering into insurance (Patym premium payment). Incumbents have realized the need for change and “innovation”. As more InsurTechs enter the space, incumbents are becoming increasingly comfortable working alongside Technology companies (they are starting to appoint “Heads of Innovation” and create standalone teams for new affinity)

    1. What do you think are the niche areas that InsurTech could cater to?

    Dr.Sahil: There are numerous opputunities for InsurTech. There are numerous pools of customers that need to be insured. So the questionhere shifs to what should be done by the insurtechs to tap into these pools. To achieve these oppurtunities, Increased interaction between insurers, early processing and common data repository are 3 component areas that needs work on initially. For example, in case of health insurance, digital recording of medical report results, prescriptions and OPD slips saves huge amount of processing time (even for third party administrator) for the customer. Moreover, creating a central repository of relevant data, accessible to all insurers, would avoid be beneficial.

    Aparajit: India is one of the fastest growing insurance markets in the world. Yet,it has less than 4% penetration. InsurTech is an necessary means of reaching out to less insured tier II and tier III cities, which entails high capital costs if done in the traditional way. Secondly, unorganized sector workers are more likely uninsured for most part. Insurtech could bridge this gap through digital customer onboarding, virtual distribution of policies, e- kyc etc Digital Customer acquisition, identity verification (through e- Aadhaar), quick accessing of product details as per customer needs etc could be done without the need for physical infrastructure. Thus, API driven InsurTech would be the key to solve the low penetration problem in India.

    Neerav : there are two  types of distributors-  retail and corporate. Corporate have broadly foussed on launching Apps say, a wellness app for pharmacy buying and telecalls. Gradually, it will be expanding to other customers (retails). The main focus would be on customers in tier II cities and rural areas, rather than in metrocities.

    Rahul: InsurTech has prospective future in Drone insurance. The upcoming use for electrical vehicles opens up doors for new product- electrical vehicles insurance. InsurTech also has huge scope in Micro insurance and insurance in sharing economy. 

    1. Personal Data Security is one of the biggest challenges India is facing. How are the new Start ups assuring the customer data safety?

    Dr.Sahil: InsurTech is all about data. And Tech doesn’t happen overnight. It has various layers that need to be designed before a robust technology takes form.

    1. Functionality or purpose of the innovation
    2. Independence in the working
    3. The Load taking capacity
    4. Security measures

    Younger population currently prefers hassle free processing through digital platform, hence data security is not the first thing on mind. This is surely a big challenge, but this is a task for a later stage. Moreover, In India, Most insurtechs are intermediaries and the essential processes like underwriting, policy issue, claim settlement are done at the insurers’ end. So in ideal situations, insurers should be responsible for Data security. Alternatively, Government, a more informed member, should take responsibility to ensure data security and measures in case of a data leak where parties involved are punished.

    Aparajit: InsurTechs abide by the data safety protocols, system audits reports and security protocols mandated by IRDA. Mostly all the Servers are located in india, which reduces risk to considerable extent. However, data threat is very much of a real problem and IRDA will come up with new measures in due course of time to tackle this effectively.

    Neerav : Big companies are mainly following European data security standards and

    Guidelines and hence are legally insulated. But in practical sense, there are still gaps. Risk prevails. Challenges are there but we will figure out more ways. Infact, this isone of the many reasons, incumbents are hesitant to invest in newbies.

    Rahul: Typically, start-ups are built on AWS[8] or MS Azure or GCP(cloud based platforms) which comes with in-built security features  that incumbents who use on-premise services would not have access to. Moreover, Incumbents tend to be more vulnerable since they are the targets of cyber criminals owing to the size of their operations. Typically, leading InsurTech companies with increasing investments (Series A/B) have a full-service cyber security team (but this varies by company).

    1. How can we increase the awareness about Insurance in India?

    Dr.Sahil: Agents, more often than not, focus on appraisal and incentives. Similarly, customers are concerned with cheaper premium with more benefits. Improving customer welfare is hardly talked about. This is a consequence of lack of awareness. Insurer should focus on post sales engagement. Inception of a chat bot or common call centre, agnostic touch point not represented by any one company could be a innovative start.

    Aparajit: Social media and search engines playing a major role in creating awareness- like  insurance specific pages on facebook, Linkedin. API culture of InsuTech also actively creates awareness. For the benefit of customers, simplification and bullet pointing the terms and conditions in policy underwriting is a suggestion.

    Neerav: Most effective way is ‘word of mouth’. Customers will do away with agents, only if they see a better alternative in new technology. Though Advertising is effective promotion, it has a limited impact. Lack of awareness has negatively impacted customers’ welfare for a long time.

    1. In my opinion, one of the implications of digital insurance is lesser personal contact and more digital interaction between the agents and the customers. Do you think this could transform into challenge in any context?

    Dr.Sahil: As mentioned before, Agent is certainly more concerned about his benefits. Post sale of product, subsequent contact with agent will be for claim processing and settlement or maturity. thus, evidently, it is more profitable to be more interactive with the insurer. Most queries by the clients are not complex or tech related (like clauses of a claim) and could be answered by Chatbots. Chatbots infact make his process more efficient- make it phygital- physical person plus digital model. Many Insurers like policy bazaar, HDFC have already employed this technology. Is time agents also adapt to this change.

    Aparajit: Unlike popular belief, digitalization can infact improve the productivity of Agent if taken advantage of. Typically, an Agent could contact 2-3 clients per day, given the distance and time factor. Digital arrangement is cost effective in the sense that it reduces transaction costs and travelling time, increases agent productivity and outreach.  Tier II and III cities are becoming with active on online platforms and are looking for online modes of communication. Voice and video could become the new mode of communication, the new normal.

    Neerav: Not really. This was a problem of past. On the contrary, InsurTech could make huge difference in Tier II and III cities which are highly dependent on agents. InsurTech would promote awareness, and provide more transparent information and advice unlike an agent. Agents could still be a source of contact forsecond opinion, but InsurTech could replace agents at primary level.

    Rahul: It is difficult to say certainly. For more established agents/brokers who own large books, they might just return to business as usual The younger generation of agents & brokers might accept the support that digital platform provides (lower commissions but higher volume) since they are less embedded in the “old ways”. It is also important to consider that customers at different points in their life would want different levels of service ranging from digital to Face-to-Face.

    1. IRDA has been welcoming to the changes in the sector. Do you think there is more to be done?

    Dr.Sahil: IRDA has done a great job so far in welcoming InsurTech into the country and establishing the sandbox. But It has to move beyond the role of a regulator and expand its capabilities in technology and insurtech.

    Aparajit:  Yes, there is a lot of scope for IRDA as a regulator. But the pace has been set, which is a progressive step. Finance ministry and IRDA could promote digitalization and modrenization in LIC.

    Neerav: No. IRDA has been very supportive and cautious. As long as the product quality meets the standards, IRDA would approve and promote the product and the firm. Although, may be Public sector firms in the economy could be given a nudge by the government and IRDA.

    Rahul: Sandbox is a good starting point and  Standardization of clauses, exclusions and claim settlements in Health is a welcome move. However, there is a  Lack of clarity on policy wordings and interpretation which makes it harder for brokers/customers to compare products on features beyond price. In addition, there is a need for Centrally pooled underwriting capacity for innovation. This is a global problem where any start-up or platform which requires “product innovation” in insurance has to chase multiple carriers. Similar to how the IRDA used to operate the Third-Party motor pool, it should consider operating an innovation pool for capacity (application system like Sandbox)

    1. Covid 19 is the biggest pandemic any country has faced so far. Yet, it is believed that Covid could in fact accelerate digitalization. Do you believe that? Do you think this holds true for India? What will be its short term and long term impacts?

     Dr.Sahil: Covid has succeded in driving a behavioural change in the customers. People have become more adaptive to digitalization of processes. This could be a long lasting effect. Yet, this seems to a  very limited group, expansion of which depends on the InsurTechs now. However, In my opinion, InsurTech per se is covid independent.

    Aparajit:

    Traditionally, There are 4 distribition channels for insurance- bancassurance, agency, direct sales and brokers and corporate agents. Prior to Covid, agency and bancassurance owned  major market share and digital platforms have less than 5% contribution. But currently, with  bancassurance and agency which are not technologically prepared, are shut and digital platforms have taken their place. Policy bazaar’s business has increased by 30% due to their digital front which is certainly going to sustain even when bancasssurance and agents revive. Thus, in this way, InsurTech will be efficient, removing manual and menial (repetitive) works. Some jobs would become obsolete, and those employees could be used for other human intensive activities. Though motor and travel insurance companies have expected short term losses, these can be recovered as the industry revives.  Insurtech was initially met with scepticism. Adopting digitalization was considered “optional”. Covid has certain ways exposed the inefficiencies in the industry. It is now a question of how fast industry can adopt technology for the long term benefit.

    Neerav: Covid infact has a multifold effect on the industry. It could change the business is done by the insurers. Gradually, a virtual work culture may develop, where client meetings are held digitally. This is entail large cost benefits.  Smaller cities and towns are moving towards digital payments and service, which has become a necessity now. It also achieving a gradual behavioural change and adaptation to technology. Insurance industry will see a change

    Rahul: Some B2B InsurTechs (like policybazaar.com, Metamophsys) have seen several inquiries come in and sales cycles shorten. Executives understood the limitations of not having digital capabilities to administer policies, renewals and claims remotely, and incumbents are inclining rapidly towards digital operations. This effect is bound to remain for a long period. Moreover, Awareness of the importance of health insurance is likely to remain. Health Insurance was one of the few segments to maintain positive YoY growth in April and May 2020)

                Presently, nearly 60- 65%  of population in India is young. They would form a major share of insurance demand in the forthcoming years and InsurTech and incumbents should be prepared for this. Demand for Renters policies and gadget protection policies will increase rapidly. Health Insurance also holds more oppurtunities for innovation and disruption. A more customer centric approach will pave the way for InsurTech.

    Evidently, Insurtech needs to happen as it is an effective way to create awareness among customers, for them to look beyond return on investment or fear. Insurance is a precaution against an eventuality and should be considered a long term investment.

    Appendix

    List of InsurTechs in India

    India: InsureTech Acitivity (Sorted by Type and then Alphabetical Order)
    Name Type Description Founded in Location
    Konsult Enabler Mobile app offering health consultations with potential insurance leads 2015 Delhi
    SatSure Enabler Crop damage assessment service 2015 Bangalore
    Trak N Tell Enabler A leading telematics solution provider 2009 Delhi
    BharatSaves Enabler Online insurace shopping by Google N/A Bangalore
    Xceedance Enabler Insurance analytics and consulting to P&C carriers 2013 Bangalore
    Senseforth Enabler Conversational AI – has developed SPOK, an email bot HDFC Life Insurance 2012 Bangalore
    Ask Arvi Enabler Health Insurance Assistant / Conversational AI 2017 Mumbai
    Girnar Software Intermediary IT company offering mobile and web solutions. Operators of CarDekho.com car buying portal 2007 Jaipur
    Demyto Intermediary A portal for car services with the ability to request an insurance quote 2015 Pune
    EasyPolicy Intermediary Life and P&C insurance comparison site 2011 Noida
    Wishfin Intermediary Insurance and finance marketplace, formerly known as Deal4Loans 2015 Delhi
    Pickme India Intermediary Gadget insurance 2011 Mumbai
    YuMiGo Intermediary Travel insurance aggregator 2015 Delhi
    Turtlemint Intermediary Insurance aggregator with online quotes and form assist 2015 Mumbai
    RenewBuy Intermediary Car insurance aggreagtor 2015 Noida
    Coverfox Intermediary Insurance aggregator with online quotes and form assist 2013 Mumbai
    ETInsure Intermediary Insurance aggregator with online quotes and form assist 2016 Delhi
    121Policy Intermediary Insurance aggregator with online quotes and form assist 2016 Kolkata
    GIBL Intermediary Insurance aggregator with online quotes 2013 Kolkata
    GramCover Intermediary An insurance marketplace for the rural sector. 2016 Delhi
    PolicyMantra Intermediary Insurance aggregator with online quotes and form assist 2010 Mumbai
    PolicyBazaar Intermediary Insurance aggregator with online quotes and form assist 2008 Gurgaon
    CarDekho Intermediary Car search portal that also provides online car insurance quotes (Subsidiary of Girnar) 2016 Gurgaon
    PolicyBoss Intermediary Online insurance aggregator 2003 Mumbai
    Acko General Insurance Primary India’s first online insurance company 2017 Mumbai

    References

    [1] Moral Hazard is the case where the insured assumes more risk, since the burden of the loss is borne by someone else( insurer)

    [2] Blockchain or distributed registry technology is a digital ledger that stores active transaction data without intermediate control by using a consensus system to validate transactions. Blockchain operates on a principle of transparency for fixed record keeping.

    [3] InsurTech -Working Group Findings & Recommendations (IRDA)

    [4] InsurTech -Working Group Findings & Recommendations (IRDA)

    [5] InsurTech -Working Group Findings & Recommendations (IRDA)

    [6] InsurTech -Working Group Findings & Recommendations (IRDA)

    [7] Internet of Things

    [8] Amazon Web Services

    This is a working paper. Comments are welcome and can be forwarded to aqf19surya@mse.ac.in
  • UAE-Israel Deal: An Analysis of its Regional Impact

    UAE-Israel Deal: An Analysis of its Regional Impact

    Introduction

    The recently brokered Abraham Accords Peace Agreement between the United Arab Emirates and Israel marks the beginning of the potential shift in West Asia’s existing power relations. Driven by their security interests, and in an attempt to amplify their power projections in the region, the two countries have come together, in what is being seen, as an opposition to the Iranian axis of influence. Although the normalization of relations with Israel marks a huge setback for the possibility of a Palestinian Statehood, several Arab countries are expected to jump on the bandwagon, with Bahrain having already concluded a treaty after UAE. This article highlights the eclectic mix of reactions from various players in West Asia and the potential opportunities and setbacks it brings with itself.

    Palestine

     Several countries held strongly pro-Palestine policies during the Cold War and decolonization period. However, in the last few decades, many have established ties with Israel; Egypt in 1979, and Jordan in1994 and now UAE and Bahrain in 2020. That being said, majority of the Arab and Gulf countries still officially do not recognize Israel. The United Arab Emirates announced its decision to normalize relations with Israel on 12th August 2020. There are many reasons why UAE and Bahrain decided to establish diplomatic relations with Israel; according to some analysts it is to counter Iran’s influence in the region, but for some it is also to establish trade and business contacts.

    However, do these developments indicate that countries in the Arab world are moving gradually into accepting Israel’s occupation of Palestinian lands as ‘fait accompli’? A significant development that needs to be recognised is the fact that many West Asian countries no longer demand the return of Palestinian lands as a precondition to normalizing ties with Israel.

    The Palestinians in the West Bank and Gaza have strongly criticised the deal and see it as betrayal of their rights and cause by the international community.

    It is long-known that Israel will not return to pre-1967 boundaries; in May 2020 Benjamin Netanyahu explicitly stated his plan to annex the West Bank. He has, however, postponed the implementation of his decision, probably indefinitely, in the interests of the deal that is likely to benefit Israel greatly.

    The Palestinians in the West Bank and Gaza have strongly criticised the deal and see it as betrayal of their rights and cause by the international community.  Banners  displaying “Treason” and “No to normalization with the occupier’ have come up across the region.  The Palestinian Authority, in very obvious response, have rejected the deals. These accords, as they rightly fear, affect the future of Palestinian sovereignty and legitimize Israel’s occupation.

    Turkey  

     President Recep Tayyip Erdogan sees himself as the champion of Muslims ever since he came to power in 2002. Under Erdogan, Turkey has pursued a clear pro-Palestinian stance. Turkey has indeed provided aid to Palestine at various times, including during COVID-19. It has criticized Trump’s peace plan for the Israel-Palestine conflict, for ignoring Palestinians’ legitimate rights. Not surprisingly, Turkey is clearly unhappy with UAE’s and Bahrain’s steps to normalize ties with Israel. Turkey has threatened with the option of halting diplomatic relations with UAE over the deal.

    However, for Palestinians Turkey’s statements ring hypocritical and hallow. Turkey was one of the earliest and the first Muslim majority state to recognize Israel in 1949. Turkey and Israel have a long history of intelligence cooperation. Even in the current situation, Turkey is focused more on dealing with the UAE on this issue, rather than Israel. Nevertheless, speaking for Palestinian rights in the international forum is equally important. In that respect, Turkey’s voice in support of the Palestinian cause is an important one.

    Saudi Arabia

     Saudi Arabia, long seen as the champion of Islamic nations, particularly in view of the fact that it is home to the two holiest shrines of Islam. Therefore, this peace agreement is a shock to the conservatives who form the majority in the Kingdom. This move by the UAE is seen as going along with the Jewish regime that denies the rights of the Palestinian Muslims. However, the Foreign Minister, Faisal bin Farhan Al Saud said the deal could be seen as positive, but his country will not normalize relations until peace is signed with the Palestinians,  within the framework of the Arab Peace Initiative.  Saudi Arabia’s track record of its unwavering support to the Palestinian cause from the days of the Yom Kippur war, also known as Ramadan War, makes the nation’s stance on the ‘Abraham Accords’ more influential than any other Gulf country. The advocacy for Palestinian state runs deep in the Saudi people. As a result, Saudi leadership’s slightest inclination towards the agreement could spark unrest among its citizens.

    The current regime under the Crown Prince of Saudi Arabia, Mohammed bin Salman (MBS), who is a very capable leader compared to his predecessors because of his broader outlook to mend diplomatic ties with the regional enemies, yields an element of uncertainty as he may be inclined towards the accord. The political and ideological differences between the people of Saudi and their leader might spark cynicism towards the government; hence, support for the accord is implausible in the short term.

    Israel, which shares the Red Sea coastline with the country and is a major player in technology innovations in the region, makes it an ideal ally for the Kingdom.

    The idea, however, is not wholly inconceivable because of MBS’s Vision 2030. Upon ascending the throne, the Crown Prince has constructed an elaborate plan to detach the Kingdom’s dependence on its natural resources and focus on bringing in diverse investments into the country. One of the main plans is to develop the Red Sea Coastline by exploiting its tourism prospects by building a smart city. Israel, which shares the Red Sea coastline with the country and is a major player in technology innovations in the region, makes it an ideal ally for the Kingdom. One of the other factors that could generate a coalition between Saudi Arabia and Israel is their common enemy, Iran.

    If MBS does accept the accord, it may not come as a surprise, but that does not warrant the fact that there is a high possibility of the decision shocking many conservative and religious establishments.  In retrospect, that could give birth to the “new” Saudi Arabia that the crown prince has promised to build.

    Qatar

    Qatar, which is considered the most developed state in the Gulf region, is in the middle of a diplomatic standoff with the regional players. Its dispute with the two major states, Saudi Arabia and UAE, has made the state go out of its way to establish diplomatic ties with parties that are not particularly approved by the GCC. The state has not given any official statement on the accord, but it’s closeness with Iran may be taken as an unofficial veto to the accord in itself. Qatar’s close relationship with the US and Iran has been a subject of debate ever since the Gulf crisis, but the state has somehow managed not to let the relationship cut across each other. This particular agreement with Israel orchestrated by the Trump government could pressure Qatar to push and resolve its issues with the UAE.

    Like any other Arab country, Qatar has advocated for the Palestinian state. It took it a little further by investing in the Gaza Strip, funding welfare payments to the coastal territory. One can suspect that the Emirati’s decision to form a coalition with the Israeli state will only deepen the ties between Qatar and Palestine.

    Though the Qatar government has been silent about the accord, Doha based news media, Al Jazeera has not shied away from raising concerns regarding the agreement. It even went to the extent of calling the accord ‘PR stunt’ initiated by the UAE. It’s support to Palestine and capitalisation of the hashtag ‘normalization as betrayal’ have received a lot of criticism from those countries that support the agreement. Qatar has always been hostile to Israel’s treatment towards the Palestinian state but has managed to have practical relations with Israel.

    Iran  

    As the world witnesses the coming together of the United Arab Emirates and Israel, two of the former adversaries, it comes as no surprise that Iran has been aggressively lashing out against the deal. With Iran still reeling under the economic pressure of the US sanctions, President Rouhani has called the deal a ‘betrayal’, aimed at satisfying the United States at a time when President Trump prepares himself to run in the national election in November. The leader of Iran-backed Hezbollah has also condemned the deal on similar grounds. Iran’s disapproval stems from two main factors – first, from its support for the Palestinian statehood; and second, more realistically, due to the increasing influence of Israel-United States nexus in the region and consequently its declining axis of influence. Iran’s insecurity is speculated to have stemmed from the confluence of actors that oppose the Islamic Republic’s attempts to establish its hegemony in the region. The confluence opens up the possibility of shifting the regional balance of power in favour of Israel, and Saudi Arabia, under the shadow of the United States. While Saudi Arabia and Israel do not yet have an official diplomatic relationship, various reports suggesting backdoor diplomacy between the two countries have surfaced over the years. The common factor bringing the two countries together has most often been assumed as the perceived threat from Iran.

    Iran and UAE, on the other hand, while maintaining a meaningful trade relationship, continue to have persistent sources of bilateral tension.

    On the other hand, while Iran and Israel have often been engaged in rhetoric of bellicose jingoism towards one another, it is essential to note that both the countries maintained a friendly relationship before the Iranian revolution of 1979, with Iran being the second Muslim country recognizing the state of Israel.

    Iran and UAE, on the other hand, while maintaining a meaningful trade relationship, continue to have persistent sources of bilateral tension, one of which is the unresolved territorial dispute over the islands of Greater Tunb, Lesser Tunb, and Abu Musa, which lie near the critical Strait of Hormuz, providing access to key shipping lanes. Despite UAE’s historical claims over their sovereignty, the islands that were forcefully occupied by Iran continue to be a strain in the relationship between the two countries. A second irritant is a growing relationship between UAE and the United States, with the former becoming one of the largest importers of US weapons and providing the US with military bases and intelligence on Iran. Worried about the growing Iranian aggression, the country has maintained a strong security relationship with the United States and has often supported the UNSC resolutions to bar sensitive materials and technology to Iran.

    Yemen

    The conflict in Yemen that began to unravel with the spread of Arab Spring in 2011 has resulted in an unprecedented loss of civilian lives across the country, making Yemen one of the world’s worst humanitarian crises. The Israel-UAE deal, which reflects the beginning of normalization of ties between Arab countries and Israel, cannot be seen in isolation from the region’s larger volatile landscape. The Peace Treaty, as it is being termed, brings with itself a plethora of threats that seek to shift the existing power relations, without aiming at the cessation of violence. UAE’s increasing outreach must be looked at in the context of its increasingly interventionist policies, especially in Yemen. The deal may ultimately lead to more interference and militarization in Yemen, prolonging the prospects for conflict resolution, and sustaining hostile conditions.

    Varied responses to the deal can be seen with the Yemeni government, and the Houthis, an armed group championing Yemen’s Zaidi Shia Muslim minority, coming out in opposition to the deal in a bid to continue their support for Palestine. On the other hand, it comes as no surprise that members of the Southern Transitional Council (southern separatists), which gets its support from the UAE, have applauded the treaty to build cooperation between UAE and Israel.

    Interest and interference in Yemen are of tremendous strategic significance to both Israel and UAE.

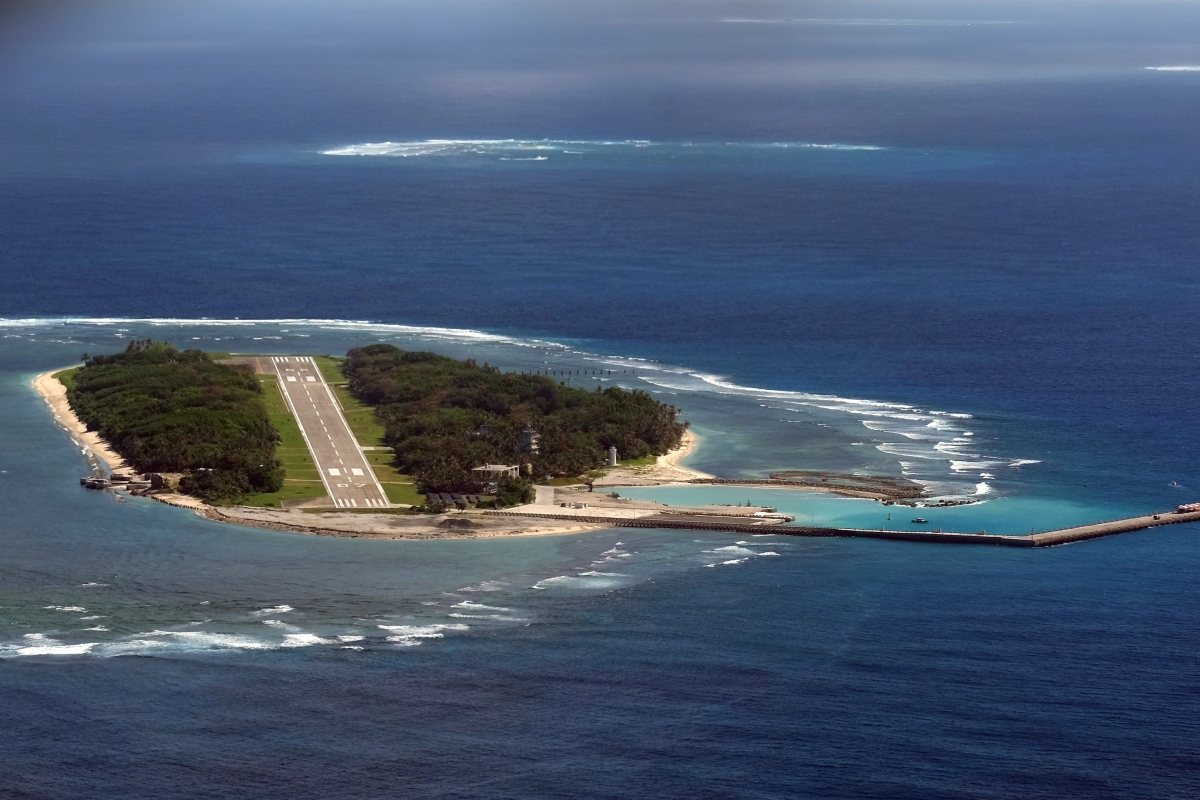
    Interest and interference in Yemen are of tremendous strategic significance to both Israel and UAE. In a show of its strengthening military projection, UAE seized control of the Yemeni island of Socotra, located in the Indian Ocean,allegedly allowing Israel to establish its presence in the region. The archipelago sits at a crucial strategic position en-route to Bab el-Mandeb, providing access to key shipping lanes.

    On the other hand, while there exists no diplomatic relationship between Yemen and Israel, the latter has often been seen intervening in the ongoing conflict in Yemen, “under the pretext of defending its interests in the Red Sea and the Strait of Bab-El-Mandeb”. With a military base already constructed at Emba Soira in Eritrea, Israel continues to increase its strategic presence across the Strait. Further, as speculations about the possible Houthi-Iran cooperation spread across the region, Israel’s surveillance centres continue to monitor the armed group’s actions and other actors in Yemen.

    Conclusion

    Palestine is a very sensitive and rousing issue for most of the citizens in West Asia. It is a shared memory of betrayal and expulsion; indeed, many politicians in West Asia use Palestine as an element in their speech and citizens also use it during slogans referring to Palestine protests.

    That being said, these deals are coming at a time when Israel is increasing its hawkish behaviour towards the Palestinians. Once the annexation happens, one cannot help but wonder how it could change the landscape of West Asia. Thus far, the progress made is the mild indication of some major players in the region favouring the accord.  Analysts suspect that the support for the accord will gain momentum in the long-term side-tracking religious, cultural and social identities to maintain diplomatic relations for economic growth.  If all countries, therefore, become friendly with Israel, will the annexation only receive loud threats with no actions?

    This study is put together by Dharika Athray, Rupal Anand, and Vrinda Aiyaswamy. All of them are Research Interns at TPF.

  • Chinese Economic Sops over the South China Sea: A Mixed Bag of Successes

    Chinese Economic Sops over the South China Sea: A Mixed Bag of Successes

    The South China Sea is a resource-rich sea space and its net worth is estimated to be US$ 2.5 trillion.[i]  The proven oil reserves are around 7.7 billion barrels and natural gas reserves could be around 266 trillion cubic feet.[ii] The Chinese strategy in the South China Sea against other claimant States is a mix of aggressive posturing including the threat of use of force as also offering economic incentives and sops such as ‘joint development of resources’ in the contested waters.

    Deng preferred a “moderate approach” i.e. “sovereignty remains ours; shelve disputes; pursue joint development.

    The idea of joint development can be attributed to Deng Xiaoping, the Chinese leader and author of market-economy reforms in the 1980s that earned him the title of ‘Architect of Modern China’. Deng preferred a “moderate approach” i.e. “sovereignty remains ours; shelve disputes; pursue joint development.”[iii]


    Map Credit: The Australian Naval Institute

    China’s current thinking on joint development of resources in South China is built around at least seven policy choices i.e. (a) promote good faith in the South China Sea; (b) limit unilateral activities in disputed areas; (c) focus on less-sensitive areas of the South China Sea; (d) reach joint development arrangements by establishing relevant working mechanism; (e) begin the process in areas where there are only two claimants; (f) define sea areas for the joint development by seeking consensus, and (g) discuss the feasibility of setting up a Spratly Resource Management Authority (SRMA) with supranational character.[iv] Further, it has been argued that the ASEAN-China Single Draft Negotiating Text of the Code of Conduct (COC) is “conducive to creating benign bilateral relations, which serves as a prerequisite to joint development”.[v]

    The general belief among the claimants is that China thinks ‘what is mine [Chinese] is of course mine, but what is your [claimants] is also mine’

    However, the above policy choices for joint development and intention are flawed and dismissed by the aggrieved claimants of the South China Sea. The general belief among the claimants is that China thinks ‘what is mine [Chinese] is of course mine, but what is your [claimants] is also mine’; i.e.  Chinese joint development initiatives are based on the wrong assumption that what belongs to China is for China only to develop, and what belongs to other claimants is for development.

    In 2018, China and the Philippines signed a Memorandum of Understanding on Cooperation on Oil and Gas Development. President Xi Jinping urged President Philippine President Rodrigo Duterte to “set aside disputes, eliminate external interference, and concentrate on conducting cooperation, making pragmatic efforts and seeking development”; furthermore, “both sides can take a ‘bigger step’ in the joint development of offshore oil and gas”.[vi] The Philippines proposed a “60-40 sharing arrangement in its favour” and both sides could then develop the “Reed Bank, the main site of the oil and gas reserves, despite the arbitration award declaring that Manila had sovereign rights to exploit them”.[vii]

    Similarly, Brunei has an ongoing arrangement with China on bilateral joint development/cooperation in the South China Sea. Economic and strategic considerations are Brunei’s twin drivers; it has been “pushing hard to diversify its economy away from the oil and gas industry” for a long time and the “unstable oil market, a slow foreign investment growth (especially in non-oil and gas sector) and a contracting national GDP” has acted as a catalyst to diversify and “joint development” is an integral part of Brunei’s wider economic diversification strategy. [viii]

    Unlike the Philippines and Brunei, Malaysia and Vietnam have shied away from joint development of resources with China in the South China Sea.

    Unlike the Philippines and Brunei, Malaysia and Vietnam have shied away from joint development of resources with China in the South China Sea. This is despite the March 2005 China, the Philippines and Vietnam Tripartite Agreement for Joint Marine Scientific Research in Certain Areas in the South China Sea by respective national oil companies.

    Malaysia is not averse to joint development with other claimants except China and at least four such projects were undertaken i.e. (a) Malaysia-Thai Joint Development Authority in the Gulf of Thailand based on the 1979 MOU; (b) 1992 MOU which designates overlapping continental shelf claims (about 2000km square) in the Gulf of Thailand as Commercial Arrangement Area (CAA); (c) the 2009 CAA between Brunei and Malaysia; and (d) Fisheries MOU between Malaysia and Indonesia, quasi-joint exploitation of fisheries resources, in overlapping claim area of about 14,300 square kilometres in the Straits of Malacca.[ix]

    Vietnam’s boundary and territorial disputes with China in the South China Sea including clashes over the Parcels have resulted in mistrust and preclude joint development with China. In essence, Vietnam does not accept joint development in areas that belong to Vietnam according to the UNCLOS 1982.

    Vietnam promotes international cooperation on resource development and has a rich body of laws to support such initiatives such as the 1982 United Nations Law of the Sea, the Petroleum Law (Article 3, No. 12), the Navigation Law, Fisheries Law, the Law on Natural Resources and Environment of Sea and Islands (Article 4, No. 5), the Tourism Law, and the Mineral Law. However, its boundary and territorial disputes with China in the South China Sea including clashes over the Parcels have resulted in mistrust and preclude joint development with China. In essence, Vietnam does not accept joint development in areas that belong to Vietnam according to the UNCLOS 1982.

    The US rejects Chinese maritime claim in the South China Sea and proclaimed “any PRC action to harass other states’ fishing or hydrocarbon development in these waters – or to carry out such activities unilaterally – is unlawful.”[x]Furthermore, while extending help to Vietnam on the matter, US Secretary of State Michael Pompeo announced that “America stands with our South-East Asian allies and partners in protecting their sovereign rights to offshore resources, consistent with their rights and obligations under international law.”

    Notes

    [i] “China Escalates Coercion against Vietnam’s Longstanding Oil and Gas Activity in the South China Sea”, https://china.usembassy-china.org.cn/china-escalates-coercion-against-vietnams-longstanding-oil-and-gas-activity-in-the-south-china-sea/  (accessed 15 September 2020).

    [ii] “South China Sea: Beijing has a major natural advantage in the geopolitical power game”, https://economictimes.indiatimes.com/news/defence/south-china-sea-beijing-has-a-major-natural-advantage-in-the-geopolitical-power-game/articleshow/76423659.cms (accessed 15 September 2020).
    [iii] “Xi Jinping and China’s Maritime Disputes”, https://taylorfravel.com/2013/08/xi-jinping-and-chinas-maritime-disputes/  (accessed 15 September 2020).
    [iv] “Joint development in the South China Sea: China’s incentives and policy choices”,https://www.tandfonline.com/doi/full/10.1080/24761028.2019.1685427  (accessed 15 September 2020).
    [v] Ibid.
    [vi] “China Focus: Xi, Duterte meet on pushing forward ties”, http://www.xinhuanet.com/english/2019-08/30/c_138350348.htm  (accessed 15 September 2020).
    [vii] “China’s Xi sees bigger role for joint energy exploration with Philippines”, https://www.reuters.com/article/us-china-philippines/chinas-xi-sees-bigger-role-for-joint-development-of-offshore-oil-gas-with-philippines-idUSKCN1VK00M  (accessed 15 September 2020).
    [viii] “Cooperative Research Report on Joint Development in the South China Sea: Incentives, Policies & Ways Forward”, http://www.iis.fudan.edu.cn/_upload/article/files/9f/21/992faf20465fae26c23ccce1ecc6/f003a68f-eb6a-4b09-a506-3c00897b0862.pdf  (accessed 15 September 2020).
    [ix] “Cooperative Research Report on Joint Development in the South China Sea: Incentives, Policies & Ways Forward”, http://www.iis.fudan.edu.cn/_upload/article/files/9f/21/992faf20465fae26c23ccce1ecc6/f003a68f-eb6a-4b09-a506-3c00897b0862.pdf  (accessed 15 September 2020).
    [x] “China pressurizes Vietnam to cancel, compensate offshore firms operating in South China Sea”, https://energy.economictimes.indiatimes.com/news/oil-and-gas/china-pressurises-vietnam-to-cancel-compensate-offshore-firms-operating-in-south-china-sea/77189060  (accessed 15 September 2020).

    Image Credit: nbcnews.com

  • Poor Economics: Rethinking Poverty & The Ways To End It

    Poor Economics: Rethinking Poverty & The Ways To End It

    I finished Poor Economics: Rethinking Poverty & the Ways to End it, by Nobel laureates Abhijit Banerjee and Esther Duflo, this past week. Before getting on with the review, it must be said that this is an old book written almost a decade ago. A few suggestions made in the book are now being implemented as government schemes and others by private enterprises. Nevertheless, the book stands the test of time because of its focus on the fundamental approach on how to think about poverty and the factors that help sustain it.

    While the extremes are always loud, the truth mostly lies somewhere in between or somewhere that is unrelated to the needless binary. The authors understand this and try to stay away from the one-size-fits-all arguments to bring people out of poverty. Instead, they try to find solutions on a case by case basis, researching the problem on the ground and coming up with specialized and localized solutions. This problem solving is achieved with the help of the numerous Randomized Control Trials (RCTs) that have been done in eighteen countries of the developing world including India, Indonesia and countries in Sub-Saharan Africa.

    The book contains ten chapters divided into two sections, namely Private Lives and Institutions. In private lives, the authors dwell on the private problems of poor people including immunization, nutrition, education and so on. And in Institutions, they deal with social institutions of credit facilities, entrepreneurship and the politics of policymaking, which the authors feel, has a tremendous impact on the private lives of the poor.

    Early on, they introduce two graphs namely the ‘S-shaped’ graph and the ‘inverted L-shaped’ graph. The S-shaped graph represents a world with a poverty trap which the poor will not be able to get out of unless there is an intervention, through government or foreign aid.

    On the other hand, the inverted L-shaped graph represents the worldview which does not believe such a poverty trap exists. This graph posits that there is potential for growth if liberty and markets are allowed to flourish. And that foreign aid will only act as an incentive for the corrupt governments of poor countries to not provide free markets for their people.

    Although the book goes on to deal with other problems dealing with poverty, the running theme of the book is the examination of these two graphs with real-life problems faced by the poor. The readers might find themselves marking ‘S’ or ‘L’ on their book at various places (unless you’re a puritan who does not mark their book, in that case, at least you would think of ‘S’ or ‘L’). The authors argue that while there are problems where a poverty trap is obvious, there are also areas where there is no trap per se and therefore even well-intentioned interventions can prove to be counterproductive. They substantiate their claims with an eighteen-country data set which they have collected over the years through field research.

    To really answer the question of whether there are poverty traps, we need to know whether the real world is better represented by one graph, or by the other. And we need to make this assessment case by case

    The authors tell us stories of Pak Sudarno’s big family of nine children, Ibu Tina’s woes due to a robbery, Jennifer Auma’s saving method and so on. These identified lives help the reader understand the decision-making process of the poor; for example, why a poor family spends money on ‘rich food’ rather than spending money on nutrient-rich food even though their children are malnourished, or why a fruit vendor drinks an extra tea even when he is aware that saving money would mean less high- interest debt. The book goes on to provide insights on various problems including the lack of self-control, poor’s relationship with risk-taking, the present bias leading to undesirable future repercussions and so on.

    Although there is no one silver bullet to rid the poor of all their problems, the authors argue that they ‘do know a number of things about how to improve the lives of the poor’. They give us five key lessons to understand the poor better. One, they believe there is a market failure of asymmetric information wherein the poor ‘often lack critical pieces of information’. Two, the poor are responsible for too many aspects of their life; for example, think of drinking water- a poor person has to decide if he has to use chlorine in water as opposed to a richer person for whom clean water is made available by other people, therefore less decision making. Psychological researches say that the quality of the decision erodes if we have to decide so many things (thus successful geniuses and trademark attire).

    Three, there are ‘good reasons that some markets are missing for the poor or that they face unfavourable prices’, for example, the poor pay higher rates on their loans. Four, the failures in a poor country have less to do with ‘some grand conspiracy of the elites’ to maintain the status quo and more to do with avoidable flaws in the designing of public policies. And finally, five, a vicious circle of low expectations and low growth.

    To make use of these lessons, there has to be dynamic politics willing to get rid of the societal sin of absolute poverty. But the authors argue that politics and governments are, unfortunately, infested with what they call ‘three Is’- Ideology, Ignorance and Inertia. Nevertheless, the authors believe that good policies will help realise good politics. Although one could understand the pragmatism and the optimistic hue of such an argument, bad politics should not be underestimated. Bad politics could stagnate even good policies and create even further problems.

    The authors understand the complex issues of poverty and know that there is ‘no lever guaranteed’ to eradicate it. Therefore, they bank on small changes to bring about big effects, for example, one additional year of deworming for kids in Kenya brought about a 20 per cent increase in income when they became adults. In a sense, the book works itself through small steps to bring an understanding of the poor into mainstream policymaking. But as the authors acknowledge, fighting poverty is not a sprint, it is a marathon, one that is worth running. They are willing to commit to the marathon, but will governments of the developing world show such commitment? Such suspicion should last until absolute poverty is completely eradicated.

  • US-China Tensions Could Spill Into Lancang-Mekong River Basin

    US-China Tensions Could Spill Into Lancang-Mekong River Basin

     The Lancang-Mekong River is the 12th longest river and runs through six countries i.e. China (upper riparian), Myanmar, Thailand, Laos, Cambodia and Vietnam (the lower riparian)and finally discharges into South China.

    A recent US government-funded study has noted that in 2019 China held back large amounts of water upstream in dams on the Mekong River which caused a  severe drought in the downstream countries,[1] prompting a US ambassador in the region accusing China of “hoarding” water and “harming the livelihoods of millions of people in downstream countries”.[2] Likewise, another report by Stimson Centre, a Washington-based think tank, has corroborated the above and pointed that in 2019 “upstream dams at Nuozhadu and Xiaowan had restricted around 20 billion cubic meters of water between July and November” and that current “satellite images show those dams are once again poised to restrict a similar amount of water from July 2020 through the end of this year … Portions of the Mekong mainstream are once again dropping to historically low levels,”[3]

    China has dismissed the reports and the Global Times in an article cited a report by the Tsinghua University and clarified that the “river dams in China [instead] helped alleviate drought along Lancang-Mekong”; furthermore, in November 2019, the Mekong River Commission (MRC) had concluded that “the drought was caused by insufficient rainfall during the wet season with a delayed arrival and earlier departure of the monsoon rain and an El Niño event that led to abnormally high temperatures and high evapotranspiration”.[4]

    At the heart of this problem is that China has built as many as 11 dams on the 4,800 kilometres long Lancang-Mekong River that originates in the Tibetan Plateau.

    At the heart of this problem is that China has built as many as 11 dams on the 4,800 kilometres long Lancang-Mekong River that originates in the Tibetan Plateau.  The Lancang-Mekong River is the 12th longest river and runs through six countries i.e. China (upper riparian), Myanmar, Thailand, Laos, Cambodia and Vietnam (the lower riparian)and finally discharges into South China.

    China has been reluctant to share hydrological data particularly during the dry seasons and releases water during rainy seasons causing flooding in lower riparian countries. This is despite the 2002 MoU under which China had agreed to provide daily river flow and rainfall data from two monitoring stations in Yunnan Province during the wet season, and the periodic MRC Heads of Government meeting over a Summit which is held every four years.

    Earlier this year, the Chinese State Councilor and Foreign Minister Wang Yi had assured that his country would “give positive consideration to share the full-year hydrological information with Mekong countries and enhance cooperation under the Lancang-Mekong Cooperation (LMC) framework to ensure reasonable and sustainable use of water resources”.[5]

    Perhaps a recent statement by the MRC may temporarily obviate suspicions over China not sharing hydrological information on the Lancang-Mekong River which notes that it welcomes China’s sharing of data “ throughout the year” as also for the “ establishment of an information-sharing platform for water resources cooperation led by China and Myanmar”.[6] Also, during the 3rd Mekong-Lancang Cooperation (MLC) Leaders’ Meeting, the Global Center for Mekong Studies (GCMS) has been tasked to study the potential benefits from “aligning and synergizing the MLC and the New International Land-Sea Trade Corridor with a vast market”.[7]

    It has been observed that although the 1995 Agreement on the Cooperation for the Sustainable Development of the Mekong River Basin is legally binding, it “does not have a compliance mechanism such as punitive measures on the party that violates the spirit and principles of the Agreement.

    In 1995, the upper and lower riparian countries had adopted Agreement on the Cooperation for the Sustainable Development of the Mekong River Basin which lays out “principles and norms of regional cooperation in managing the river basin”. A formal dialogue process under the MRC was instituted to address issues relating to Mekong River and the Member States agreed to “promote common procedures and practices throughout the region for data collection, storage and analysis to support data sharing and integration of existing data management systems based on the voluntary participation of countries and institutions.”[8] In 2001, they adopted the “Procedures for Data and Information Exchange and Sharing,” or PDIES to enable the Member States to share data ‘to provide real-time water level information and more accurate flood forecasting.

    It has been observed that although the 1995 Agreement on the Cooperation for the Sustainable Development of the Mekong River Basin is legally binding, it “does not have a compliance mechanism such as punitive measures on the party that violates the spirit and principles of the Agreement. The conflict resolution mechanism is also not clearly stipulated”.[9] This is one of the many reasons for discord among the Parties which needs to be addressed by the MRC whose mandate includes dispute resolution.

    Be that as it may, the lower Mekong countries have set up the Mekong Water Data Initiative, and at the 10th Ministerial Meeting of the Lower Mekong Initiative (LMI) in 2017 to ‘create a robust, integrated, and transparent platform for collecting, sharing, and managing data on the Mekong River system.’[10]

    there are fears that the Lancang-Mekong River issue is slowly shaping into a major ASEAN-China bilateral issue similar to the contestation in the South China Sea.

    At another level, there are fears that the Lancang-Mekong River issue is slowly shaping into a major ASEAN-China bilateral issue similar to the contestation in the South China Sea; and the current situation is being described as “becoming a geopolitical issue, much like the South China Sea, between the United States and China,”[11] Perhaps the biggest worry is that the Lancang-Mekong River should not attract contestation between the US and China which surely is going to make the region more turbulent. It would thus be prudent that ASEAN and China work on a Code of Conduct to manage the river affairs or add more robustness in the existing dialogue mechanism over the Lancang-Mekong River.

    End Notes
    [1] “China could have choked off the Mekong and aggravated a drought, threatening the lifeline of millions in Asia”, https://www.cnbc.com/2020/04/28/china-choked-off-the-mekong-which-worsened-southeast-asia-drought-study.html  (accessed 12 September 2020).
    [2] “Water wars: Mekong River another front in U.S.-China rivalry”, https://www.japantimes.co.jp/news/2020/07/25/asia-pacific/mekong-river-us-china/  (accessed 12 September 2020).
    [3] “The next US-China battleground: Chinese dams on the Mekong River?”,https://www.scmp.com/week-asia/politics/article/3095581/next-us-china-battleground-chinese-dams-mekong-river  (accessed 12 September 2020).
    [4] “River dams in China helped alleviate drought along Lancang-Mekong, research finds”, https://www.globaltimes.cn/content/1194654.shtml  (accessed 10 September 2020).
    [5] “River dams in China helped alleviate drought along Lancang-Mekong, research finds”, https://www.globaltimes.cn/content/1194654.shtml  (accessed 10 September 2020).
    [6] “Lancang-Mekong cooperation provide stronger impetus for regional development and prosperity”, http://www.lmcchina.org/eng/hzdt_1/t1812281.htm  (accessed 12 September 2020)
    [7] “Full text of Co-chairs’ Statement on Cooperation of Synergizing the MLC and the New International Land-Sea Trade Corridor of the Third MLC Leaders’ Meeting”, http://www.lmcchina.org/eng/zyxw_5/t1808947.htm  (accessed 12 September 2020).
    [8] “Joint Statement To Strengthen Water Data Management and Information Sharing in The Lower Mekong”,
    https://www.lowermekong.org/news/joint-statement-strengthen-water-data-management-and-information-sharing-lower-mekong (accessed 14 April 219)
    [9] “Code of Conduct for the Mekong”,https://vannarithchheang.com/2018/04/04/code-of-conduct-for-the-mekong/  (accessed 12 September 2020).
    [10] “Mekong River Commission keen to improve data sharing and management in the Lower Mekong Basin”, https://mrcmekong.org/news-and-events/news/mrc-keen-data-management-in-mekong-basin/  (accessed 12 September 2020.
    [11] “Water wars: Mekong River another front in U.S.-China rivalry”, https://www.japantimes.co.jp/news/2020/07/25/asia-pacific/mekong-river-us-china/  (accessed 12 September 2020).

    Image: Mekong Riverside, Phnom Penh-Cambodia

  • Good Economics For Hard Times

    Good Economics For Hard Times

    Title : Good Economics for Hard Times

    By Esther Duflo and Abhijit Bannerjee

    Published by Public Affairs, Hachette Book Group, New York

    Year :  November 2019

    Honesty is a quality seldom found among economists. More often than not, economists refuse to acknowledge the limitations of economic models that rely on, at times, completely unrealistic assumptions. That is, fortunately, not the case with this book. This book does not over-simplify economic issues and makes a compelling argument against making sweeping generalizations in a profession that relies on studying human behaviour.

    One of the best things about this book is its accessibility, it is as accessible to a layman as it is to a seasoned economist. This book, in a significant departure from their first book Poor Economics, focuses on the burning issues of wealthy countries instead. The writing is witty and succinct, full of interesting personal anecdotes.

    They start with the politically sensitive issue of immigration and show why conventional models of supply and demand don’t work for labour markets. Conventional theory, and critics of immigration, would have us believe that an influx of immigrants would drive down wages in the area and result in job losses for the natives. But Banerjee and Duflo show that the immigrants don’t just increase the labour force, they’re also consumers. Thus, they increase demand and by extension, employment and GDP in the area. They also point out that there is no strong evidence that even large influxes impact wages severely.

    However, when it comes to growth they’re not as clear as they are about the impact of immigration. They make a case as to why nobody really knows what drives growth in the long term and why prominent growth economists (Sollow, Romer etc) were all right as well as wrong at the same time. According to them, both the optimists and pessimists make sound arguments and it is impossible to predict if growth will continue or perish given the humongous number of variables involved and the sheer unpredictability of technology.

    Their support for free trade, unsurprisingly, is not unconditional. They don’t think it is the panacea that the neo-liberal discourse makes it out to be. Expansion of trade, they believe, is the driver of despair globally because of its random behaviour as they write, “Trade has created a more volatile world where jobs suddenly vanish only to turn up a thousand miles away.” They also present evidence showing that, at times, free trade has done more harm than good and argue that the state must provide proper support to the losers from trade if they want to mitigate the damage.

    Cutting tax rates for the rich has long been argued as a certain method to improve growth by many economists. Banerjee and Duflo, however, disagree. They write “In a policy world that has mostly abandoned reason … let’s be clear: Tax cuts for the wealthy do not produce economic growth.” They argue that even the (in)famous Reagan-Thatcher era tax cuts did little to revive growth. Instead, those tax cuts, accompanied by cuts in welfare spending contributed immensely to income inequality. Advocates of tax cuts often argue that raising taxes stifle innovation, but that is clearly false as Bill Gates himself argues here.

    Where a lot of economists fail and they excel, is bringing the social science aspect into economics. They don’t see people just as means to an end (growth) and emphasize on prioritising non-economic goals that don’t necessarily result into higher growth but instead improve overall happiness, dignity, self-respect and give people a sense of purpose. According to them, in this growing environment of despair, it is important to provide people with a sense of purpose.

    They argue, quite successfully, that we should change our policy response to poverty and stop letting only poverty define poor people. They recommend that poor people be seen just like normal people who have dreams and desires and policymakers need to stop believing that they know better about what poor people need than the people themselves.

    Lastly, they say that the message of policy interventions should not be ‘you are being rescued by the state’ and instead ‘this is the state’s support to ensure you have the basic rights you deserve.’ It is vital that they’re given the respect they deserve if we want them to lead dignified lives and not make them feel like they’re living on handouts from the state as even the needy hate being dependent on others. Restoring the dignity of the poor is an important step in eradicating poverty, they say.

    This book’s brilliance, in my opinion, is evident from the fact that economists across the ideological spectrum, from Sollow to Piketty, are all in awe of this work of art. To be honest, I have learnt more about economics and policymaking from this book than I did as an economics graduate.

    The arguments put forth in this book were, to an extent, eye-opening for me. I found them compelling and I believe you will too.

    Mohit Verma is a Research Intern in TPF. He is pursuing his Masters at the Madras School of Economics (MSE), Chennai.

  • The DNA Bill And State Capacity

    The DNA Bill And State Capacity

    Aristotle suggested that transmission of heredity was essentially the transmission of information. And this information was used to build an organism from scratch inside the female womb. Although the science is primitive, he was right in how information is transmitted from parents to their offspring. Modern genetics is built on studying such information, which has been coded into each cell as DNA. Scientists can now sequence the DNA and extract valuable information about each individual and the human species. They have been able to use such information to understand humans better; for example, the identification of BRCA mutation responsible for cancer has nudged great strides in cancer biology. Another important application which has varied implications in society is the use of DNA in forensics. Although already in use since its discovery in 1995, the exponential rise in the significance of information extracted using DNA Profiling warrants regulation.

    All major nations which use DNA Profiling have legislation in place to regulate the use of the technology. However, in India, the technology is unregulated even though successive governments have worked on such legislation since 2003.

    DNA Technology Bill

    All major nations which use DNA Profiling have legislation in place to regulate the use of the technology. However, in India, the technology is unregulated even though successive governments have worked on such legislation since 2003. If global examples are not enough, the 2017 Puttaswamy judgement has made such legislation necessary. The judgement asserted that privacy is a fundamental right guaranteed by the Indian Constitution and that the right to privacy includes protection over the physical body. Therefore, for the State to collect or store DNA data, a legislative mechanism principled on necessity and proportionality is requisite.

    DNA testing is being done on a very limited scale in India. About 30-40 DNA experts are working in 15-18 laboratories. They can process only about 2-3% of the total need, and even such limited testing is unregulated and unmonitored. According to the NCRB data for 2018, although 85% of rape accused have been charge-sheeted, the conviction rate for rape is just 27.2%. This technology, however, has an excellent record of increasing conviction rates; for example, a 2006 UK parliamentary report suggested that detection of crime increased from a mere 26% to a healthy 40% after they loaded DNA samples into a national database. Apart from crime detection, the technology will also help in the identification of over six million missing persons in India. Thus, legislation facilitating DNA technology to help expedite justice is long overdue.

    The DNA Technology (Use and Application) Bill 2019 is the latest form of the DNA bill and is at the parliamentary committee stage for further deliberations. The bill talks of a national DNA data bank and a DNA regulatory board to store DNA data and regulate DNA technology used in criminal and civil cases. The bill in its current form has raised many concerns including privacy issues concerning the use of DNA data, the ‘perfunctory consent’ clause which makes it hard for an individual to deny permission to collect his/her data, ethical issues in collecting and storing DNA data in DNA banks, the fear of caste-based criminal profiling because of the endogamous nature of Indian society and so on. But the biggest concern is one of state capacity, which in a way umbrellas other concerns.

    The bill in its current form has raised many concerns including privacy issues concerning the use of DNA data, the ‘perfunctory consent’ clause which makes it hard for an individual to deny permission to collect his/her data, ethical issues in collecting and storing DNA data in DNA banks, the fear of caste-based criminal profiling because of the endogamous nature of Indian society and so on.

    Problems with State Capacity

    In young nations like India, the State, although large and bloated, is not highly efficient. This may cause even government interventions with noble intentions to backfire. Therefore, it is necessary to identify places where a lack of state capacity could cause worry for the legislation to work effectively.

    We could sum three basic concerns up from the DNA Technology bill concerning state capacity. First, the high cost of technology and the lack of basic technical training regarding data collection in a crime scene. Second, the backlog burden in the Justice system. And finally, the lack of clarity in the bill as to what is being collected and stored.

    The India Justice Report 2019 published by Tata Trusts reveal important information on the Justice system in India. Over the last five years, only 6.4% of the police force has been provided in-service training. For advanced technology like DNA fingerprinting, frontline police should have basic training and knowledge of the technology. It starts with how to read and deal with the crime scene. And without awareness, the technology cannot be exploited desirably. To go from training 6.4% to at least half the police force will be a herculean task which should be contemplated before implementing the legislation. The DNA bill gives the responsibility of developing training modules to the DNA Regulatory Board, which will be set up. But it does not provide a realistic road map to reach the desired level of training to better use the technology.

    The report also suggests that on average, per capita police spending in 2017 was Rs 820. No big or medium-sized state has spent more than Rupees 1160 per person, and Bihar has spent as low as Rupees 498. Only one state has made 100% use of the modernization funds allocated for capital expenditure and technology up-gradation. But DNA fingerprinting technology is a costly affair. Each test could cost as much as Rupees 10,000. Even if only high-profile cases use DNA tests, a robust database of DNA has to be present for effective identification from the three indices mentioned in the bill. And such collection and storage of DNA samples could become another strain in the public exchequer. The bill also mandates the use of DNA testing for criminal as well as civil cases, which could again flood the system.

    Second, DNA technology could increase the backlog burden of the already burdened system. In the US, with relatively strong state capacity, DNA backlogs are in the thousands. The National Institute of Justice (USA) reports that the current backlog of rape and homicide cases is 350,000. It also estimates that there are ‘between 500,000 to 1 million convicted offenders’ samples that are owed but not yet collected’. The FBI has a backlog of approximately 18,000 convicted offender samples. Therefore, in India with an already strained Justice system, DNA backlogs could cause worry. Also, because of the significance of DNA information, backlogs could also invoke privacy concerns.

    Finally, there is a lack of clarity. This concern, however, is not one of lack of state capacity but one of potential overreach by the State.

    The lack of strong data protection legislation in place couples such concern. As the parliamentary committee suggests, the bill can also be termed ‘premature’ regarding data protection.

    Non-coding DNA is used for identification. The bill, however, does not restrict DNA Profiling to only use non-coding DNA which cannot be used for determining personal and medical characteristics. Given that the bill mandates data from all criminal and civil cases to be stored in the National data bank, concerns of privacy impingement cannot be hushed away. The lack of strong data protection legislation in place couples such concern. As the parliamentary committee suggests, the bill can also be termed ‘premature’ regarding data protection.

    Although the bill is creating a strict code of ethics regarding collection, storage and accessibility of DNA information, it is ambiguous on the removal of data. Clause 31(3) says that DNA data will be removed if a person requested in writing to the DNA bank, given that such a person is ‘neither an offender nor a suspect or an under-trial’ and whose DNA information has entered the bank ‘through crime scene index or missing persons’ index’. But it is not clear on what will happen if they do not remove such data. It is important to answer these questions due to the significance of DNA information and the fact that the bill does not restrict banks to store only non-coding DNA. Also, these questions could raise concerns about state capacity in safeguarding important data of its citizens.

    Conclusion

    To address these concerns, building state capacity is the key. A staggered implementation of DNA technology could help in building capacity and credibility for the technology. For example, if the bill provides a roadmap of implementation- say, starting with addressing the identification of missing persons and further developing capacity for criminal and civil investigation, the allocation of resources could be streamlined. This limited implementation could also help in addressing additional issues that could arise during implementation. These details cannot be let out to be decided by a regulatory body because of the importance of DNA data and the breach of fundamental rights in collecting and storing it.

    It is said that one has to cross the river by feeling the stones. The stable rule of law and a robust data protection regime which will make sure the technology is used judicially are basic requisites for technology with societal implications. Even though DNA profiling has huge potential to expedite justice, implementation of such complex technology has to be step by step. The Parliamentary Committee on Science and Technology has been scrutinizing the bill rigorously, contemplating the varied problems that might befall the implementation of the bill. But it remains to be seen if the government will heed to such advice and not dismiss them altogether; that is if it will feel the stones or deep dive into the river without contemplating the consequences.

    Image Credit: DNA Helix Material – Gerd Altmann from Pixabay

  • What Triggered Recent Chinese Naval Exercises in the South China Sea?

    What Triggered Recent Chinese Naval Exercises in the South China Sea?

    During the last few months, the PLA Navy along with the PLA Air Force conducted several exercises in the South China Sea. China used these maneuvers to deter Taiwan against its growing relationships with the US, and as a tool of “strategic communication” to signal to the US of its military capabilities to project power and defend its national interests. There are at least five important reasons that could have triggered such aggressive posturing by China.

    First is COVID-19. After Wuhan was designated as the source-destination of COVID-19 in January this year and over 80,000 of its residents were reported to have been infected by the virus, the Chinese leadership sought to boost its image among its people who had been struggling by lockdowns.[i] In the first half of February, China chose to divert international attention away from the pandemic by deploying fighter jets and bombers to intimidate Taiwan which had been critical of China over its handling of the virus. This prompted Taipei to advise authorities in Beijing to “focus on preventing the spread of the epidemic” and admonished it for “inciting nationalism at home to shift public focus away from challenges at hand” and labelled it as a “game not worth the candle”.[ii]

    the PLA Navy, led by the aircraft carrier Liaoning, conducted naval exercises and the taskforce sailed through the Miyako Strait, Bashi Channel and the South China Seaostensibly to display its military readiness during the pandemic. 

    Also, while the global community struggled to combat the pandemic and at least three US Navy carriers afflicted by COVID-19 virus, the PLA Navy, led by the aircraft carrier Liaoning, conducted naval exercises and the taskforce sailed through the Miyako Strait, Bashi Channel and the South China Sea[iii] ostensibly to display its military readiness during the pandemic. The PLA Air Force too showcased it combat readiness and fighter jets intruded into Taiwan’s air space. However, the US responded by three-carrier deployment including dual-carrier operations; B-52 Stratofortress bombers operated from Guam and the nuclear submarines were forward-deployed to conduct “contingency response operations.”[iv]

    Second, China was rattled after the US turned the Taiwan Allies International Protection and Enhancement Initiative (TAIPEI) Act into law to show that “it has the support of both branches of government, which is required for a strong and effective U.S. foreign policy”.[v] Similarly, it also introduced a new Bill ‘Taiwan Defence Act’ in the US Congress[vi] which requires the Department of Defense to provide weapons to Taipei. The Trump administration also announced a military package worth US$ 180 million to improve Taiwan’s capability against “regional threats and to strengthen homeland defense,” [vii]

    Third, is about the Pacific Deterrence Initiative (PDI) which entails fiscal support for military activities and associated infrastructure investment plans[viii] in the Pacific Ocean. The PDI is similar to the 2014 European Deterrence Initiative (targeted against Russia) and is meant to advance US priorities in the Indo-Pacific region. It aims to “focus resources on key capability gaps to ensure U.S. forces have everything they need to compete, fight, and win in the Indo-Pacific” is conspicuously targeted against China.

    India, in response to Chinese posturing in the Himalayas, deployed its naval ship in the South China Sea. This unexpected Indian posturing challenging China in its own backyard and operating in close cooperation with the US Navy, has caused alarm bells in Beijing.

    Fourth, China is concerned about the Quadrilateral Security Dialogue (QSD), a grouping of Australia, India, Japan and the US, which China believes is meant to contain it. Since 2018, India has been hosting the Malabar series of naval exercises which include Japan and the US; but this is being expanded to include Australia. The geographic focus of the Malabar exercises had so far remained in the Bay of Bengal or the Pacific Ocean (around Guam and Japanese waters), could now shift to the South China Sea. India, in response to Chinese posturing in the Himalayas, deployed its naval ship in the South China Sea. This unexpected Indian posturing challenging China in its own backyard and operating in close cooperation with the US Navy, has caused alarm bells in Beijing.

    Chinese worries about the Quad are further aggravated after Taiwanese President Tsai Ing-wen, amid rising tensions between Taiwan and China around the South China Sea region, has called for a joint alliance of democratic nations to uphold “a strategic order that encourages cooperation, transparency and problem-solving through dialogue, not threats of war”.[ix]

    Fifth, is related to Code of Conduct (CoC) for South China Sea between China and the ASEAN. The Chairman’s Statement of the 36th ASEAN Summit has “emphasised the need to maintain and promote an environment conducive to the COC negotiations”[x] and Prime Minister Nguyen Xuan Phuc has urged China to accelerate talks on an effective and efficient COC in line with international law, including the 1982 UNCLOS.[xi] China has in the past disregarded the urgency over the finalization of the CoC and has dragged the issue far too long, but now appears to have realized that there is high degree of unity among the Member States over the South China Sea issue and attempted to reassure ASEAN of its intentions to pursue the issue hopefully in right earnest.

    Among other political, diplomatic and economic toolkits to appease the ASEAN Member States, it also chose to conduct military exercises to intimidate Malaysia, Philippines and Vietnam.

    Among other political, diplomatic and economic toolkits to appease the ASEAN Member States, it also chose to conduct military exercises to intimidate Malaysia, Philippines and Vietnam. It relented only after Philippines Foreign Secretary Teodoro Locsin Jr denounced as ‘illegal provocations’ Chinese air patrols over the South China Sea and threatened if “something happens that is beyond incursion but is in fact an attack on say a Filipino naval vessel … [that] means then I call up Washington DC,”

    China’s attempts to dominate the regional security affairs, non-adherence to the 1982 United Nations Law of the Sea, coercion of other claimants to the disputed features in South China Sea and its intimidation of Taiwan has not gone well among the ASEAN Member States. ASEAN sees US’ formidable capabilities and above all its commitment to keep the Indo-Pacific ‘free and open’ against any attempts by China, as reassuring.

    In his recent remarks at the 10th East Asia Summit Foreign Ministers’ Meeting,[xii] Secretary of State Michael R. Pompeo assured his counterparts from 17 countries that the US shares and supports the “principles of openness, inclusiveness, transparency, and respect for international law contained in the US’ Indo-Pacific vision, ASEAN’s Outlook on the Indo Pacific, and the visions of many other EAS Member States”.

    Image Credit: The Globe and Mail and VoA

    References

    [i] “China Sends Ships, Planes over Disputed Seas to Show Strength after COVID-19 Outbreak”, https://www.voanews.com/east-asia-pacific/china-sends-ships-planes-over-disputed-seas-show-strength-after-covid-19-outbreak  (accessed 08 September 2020).

    [ii] “The ROC Firmly Defends its Sovereignty: The CCP Should Immediately Stop its Military Provocations and not Misjudge the Situation”, https://www.mac.gov.tw/en/News_Content.aspx?n=A921DFB2651FF92F&sms=37838322A6DA5E79&s=3AF953C12D84A525  (accessed 08 September 2020).
    [iii] “   Chinese aircraft carrier Liaoning conducts exercises in South China Sea: PLA Navy spokesperson”, https://www.globaltimes.cn/content/1185471.shtml  (accessed 08 September 2020).
    [iv] “Pacific Fleet Submarines: Lethal, Agile, Underway”, https://www.navy.mil/submit/display.asp?story_id=112909 (accessed 06 July 2020).
    [v] “Trump and the TAIPEI Act”, https://thediplomat.com/2020/04/trump-and-the-taipei-act/  (accessed 08 September 2020).
    [vi] Under the 1978 Taiwan relations Act the United States “will make available to Taiwan such defence articles and defence services in such quantity as may be necessary to enable Taiwan to maintain a sufficient self-defence capabilities”;
    [vii] “Trump administration approves arms sale to Taiwan amid China tensions”, https://edition.cnn.com/2020/05/21/politics/us-taiwan-arms-sale/index.html (accessed 20 June 2020).
    [viii] “Investments in theater missile defense, expeditionary airfield and port infrastructure, fuel and munitions storage, and other areas will be key to America’s future force posture in the Indo-Pacific.” See “The Pacific Deterrence Initiative: Peace through Strength in the Indo-Pacific”, https://warontherocks.com/2020/05/the-pacific-deterrence-initiative-peace-through-strength-in-the-indo-pacific/ (accessed 20 June 2020).
    [ix] “Fed-Up of Chinese Threats, Taiwanese President Urges ‘Coalition of Democracies’ to Confront Beijing”, https://eurasiantimes.com/fed-up-of-chinese-threats-taiwanese-pm-urges-coalition-of-democracies-to-confront-beijing/ (accessed 09 September 2020).
    [x] “Chairman’s Statement of the 36th ASEAN Summit 26 June 2020” https://asean.org/storage/2020/06/Chairman-Statement-of-the-36th-ASEAN-Summit-FINAL.pdf (accessed 14 July 2020).
    [xi] “Pompeo: China cannot be allowed to treat the South China Sea as its maritime empire”, https://vietnamtimes.org.vn/pompeo-china-cannot-be-allowed-to-treat-the-south-china-sea-as-its-maritime-empire-21832.html (accessed 14 July 2020).
    [xii] “Secretary Pompeo’s Participation in the 10th East Asia Summit Virtual Foreign Ministers’ Meeting”, https://china.usembassy-china.org.cn/secretary-pompeos-participation-in-the-10th-east-asia-summit-virtual-foreign-ministers-meeting/  (accessed 10 September 2020).